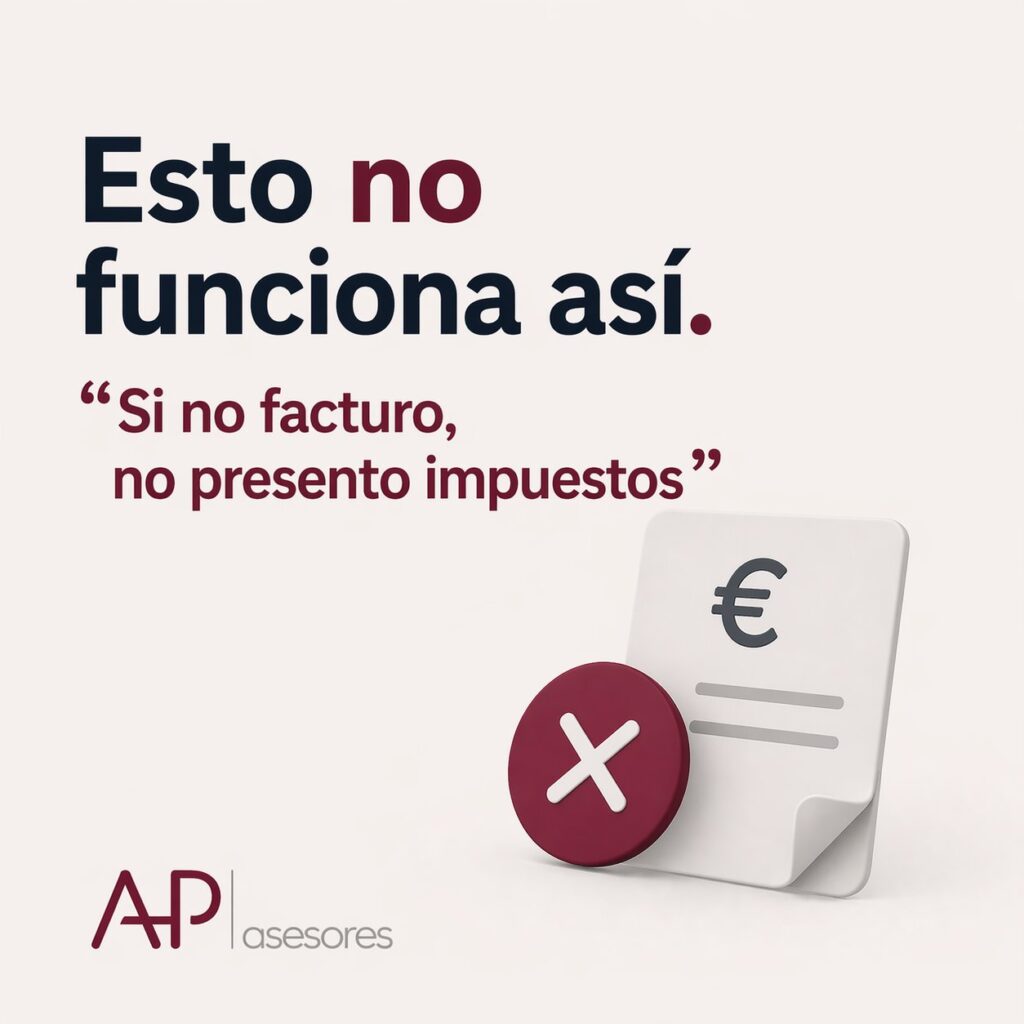
It is a simplification that often does not match reality. Even with no income in a period, tax and formal obligations may still apply: periodic VAT returns and income tax instalment payments must be filed even if they come out at zero, and a dormant company must still file Corporate Income Tax and its annual accounts.
When you assume there is nothing to file, you may end up with
- Accumulated debts.
- Surcharges and penalties for not filing.
- A false sense of control.
The key is knowing which obligations are still alive at any given time and planning them in advance.
At AP Asesores we help you anticipate those obligations so that your administration does not depend on surprises.
Legislation: art. 71 of Royal Decree 1624/1992 (VAT Regulation); art. 109 of Royal Decree 439/2007 (IRPF Regulation); art. 124 of Law 27/2014 on Corporate Income Tax.